31 August 2026
China Leather Industry H1 2026
Economic Performance, Structural Change and Market Outlook
Executive Summary
China’s leather industry faced significant pressure in the first half of 2026 amid weak global demand, raw-material price volatility and a complex external environment. Key enterprises recorded sales revenue of nearly RMB 330 billion, down 5.0% year on year. Exports declined 5.4% to US$40.9 billion, while imports rose 4.9% to US$7.9 billion.
Performance varied across segments. Tanning and footwear remained under pressure, while leather garments recorded strong growth. Raw hide and skin imports increased, but imports of semi-finished and finished leather declined. Looking ahead, the industry is expected to remain broadly stable but increasingly differentiated, with continued pressure on profitability and a stronger focus on higher-value, smarter and greener development.
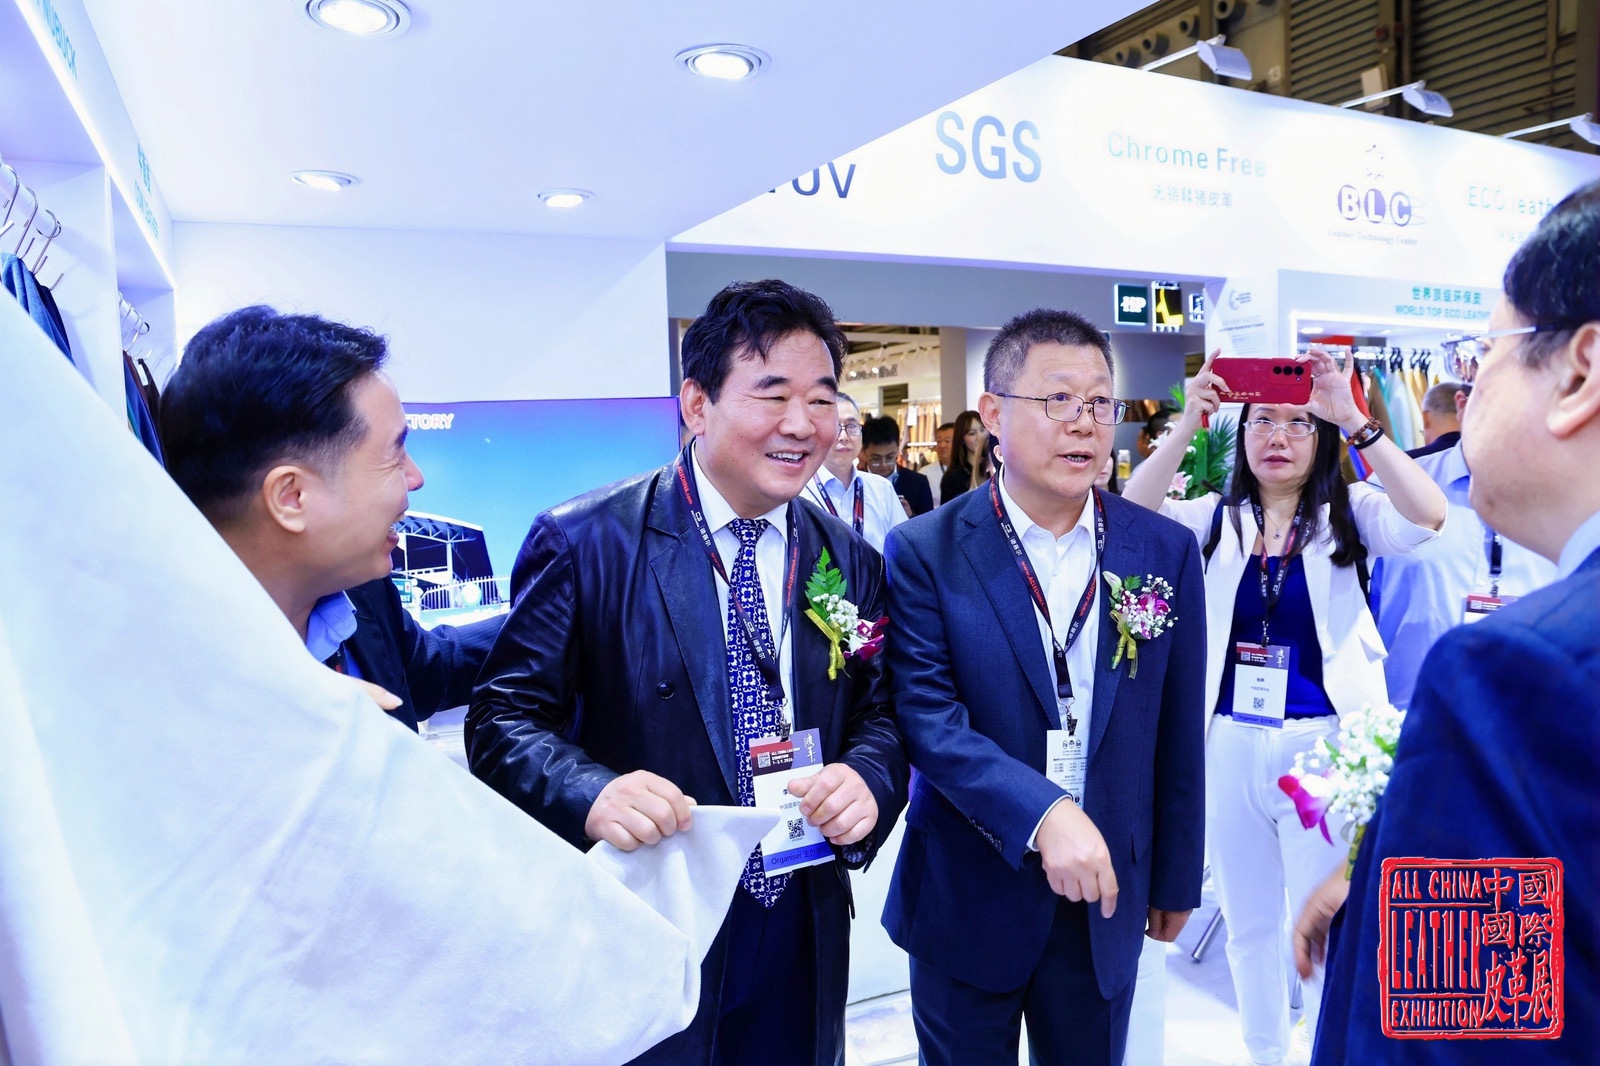
Li Yuzhong (left), Chairman of the China Leather Industry Association, and Chen Zhanguang (right), Vice Chairman of the China Leather Industry Association, at the 2026 All China Leather Exhibition (ACLE).
Key Indicators
| Indicator | H1 2026 | YoY |
| Leather industry key-enterprise sales | Nearly RMB 330 bn | -5.0% |
| Industry exports | US$40.9 bn | -5.4% |
| Industry imports | US$7.9 bn | +4.9% |
| Tanning key-enterprise sales | Nearly RMB 21 bn | -12.8% |
| Light leather output | 140 million sq m | -6.5% |
| Leather footwear output | 970 million pairs | -7.6% |
| Leather garment key-enterprise sales | RMB 2.9 bn | +25.5% |
| Travel goods & luggage key-enterprise sales | More than RMB 42 bn | -5.3% |
1. Industry Overview
In the first half of 2026, the industry came under significant pressure amid weak global demand, fluctuations in raw material prices, and a complex and rapidly changing external environment. According to statistics, key enterprises in China’s leather industry recorded sales revenue of nearly RMB 330 billion, down 5.0% year on year. The industry’s exports totalled US$40.9 billion, down 5.4%, while imports reached US$7.9 billion, up 4.9%.
2. Tanning
Key tanning enterprises nationwide recorded sales revenue of nearly RMB 21 billion, down 12.8% year on year. Light leather output reached 140 million square metres, down 6.5%.
| Trade | Volumn | Value | YoY change |
| Raw hides and skins | 749,000 tonnes | US$600m | +7.0% volume / +2.9% value |
| Semi-finished leather | 295,000 tonnes | US$400m | -5.9% volume / -14.8% value |
| Finished leather | 18,000 tonnes | US$270m | -2.2% volume / -5.0% value |
3. Footwear Manufacturing
Key footwear enterprises nationwide recorded sales revenue of more than RMB 200 billion, down 6.1% year on year. Key enterprises producing leather footwear manufactured 970 million pairs, down 7.6%.
| Trade | Volumn | Value | YoY change |
| All footwear exports | 4.29 bn pairs | US$19.83 bn | -4.6% volume / -8.6% value |
| All footwear imports | 70m pairs | US$2.58 bn | -17.3% volume / -2.3% value |
| Leather-upper footwear exports | 240m pairs | US$3.28 bn | -3.3% volume / -8.7% value |
| Leather-upper footwear imports | 20m pairs | US$1.10 bn | -14.7% volume / -2.0% value |
4. Leather Garments
Key leather garment enterprises recorded sales revenue of RMB 2.9 billion, up 25.5% year on year. Exports reached US$68.68 million, up 41.4%, while imports reached US$64.76 million, up 31.3%. Leather garments were one of the strongest-performing major segments in the first half of 2026.
5. Travel Goods and Luggage
Key enterprises in travel goods and luggage recorded sales revenue of more than RMB 42 billion, down 5.3% year on year. Exports reached US$15.48 billion, down 3.1%, while imports rose 13.6% to US$2.88 billion.
6. Market Environment: Challenges and Opportunities
Macroeconomic backdrop
China’s GDP grew by 4.7% year on year in the first half of 2026. Domestic economic recovery and policies to boost consumption and stimulate domestic demand provide support for the leather industry. At the same time, geopolitical conflicts, weak global economic recovery, international trade frictions and overseas tariff barriers continue to constrain exports, while energy-price volatility and rising raw-material costs add pressure to business operations.
The industry is also expanding its global footprint. Cross-border e-commerce and overseas warehousing are developing rapidly, while China’s complete industrial system continues to support stable industry performance.
Changing consumer demand
Consumer demand has moved beyond volume-driven growth towards higher quality, greener development and greater differentiation. Younger consumers, Chinese cultural trends, green and low-carbon consumption and the expanding silver economy are reshaping the market. Demand is also increasing for personalised and premium products, as well as small-batch, fast-response and customised orders across footwear, bags, leather garments and fur garments.
Industrial transformation
The industry is accelerating its shift towards higher-end, smarter, greener and more integrated development. Products are moving beyond low-end contract manufacturing towards higher value-added offerings and stronger proprietary brands. AI and end-to-end digitalisation are increasingly supporting R&D, production and marketing, while cleaner production and low-carbon processes continue to expand.
7. Market Outlook
The long-term fundamentals supporting China’s leather industry remain positive, with the country’s very large domestic market providing a core foundation for high-quality development. Short-term pressures nevertheless persist. Production, sales and exports are expected to remain at low growth levels throughout 2026, while corporate profitability will continue to face pressure.
Looking ahead, the industry will place technological innovation at its core, deepen brand building and design R&D, and accelerate the development of new quality productive forces to support steady, high-quality development.